On this page
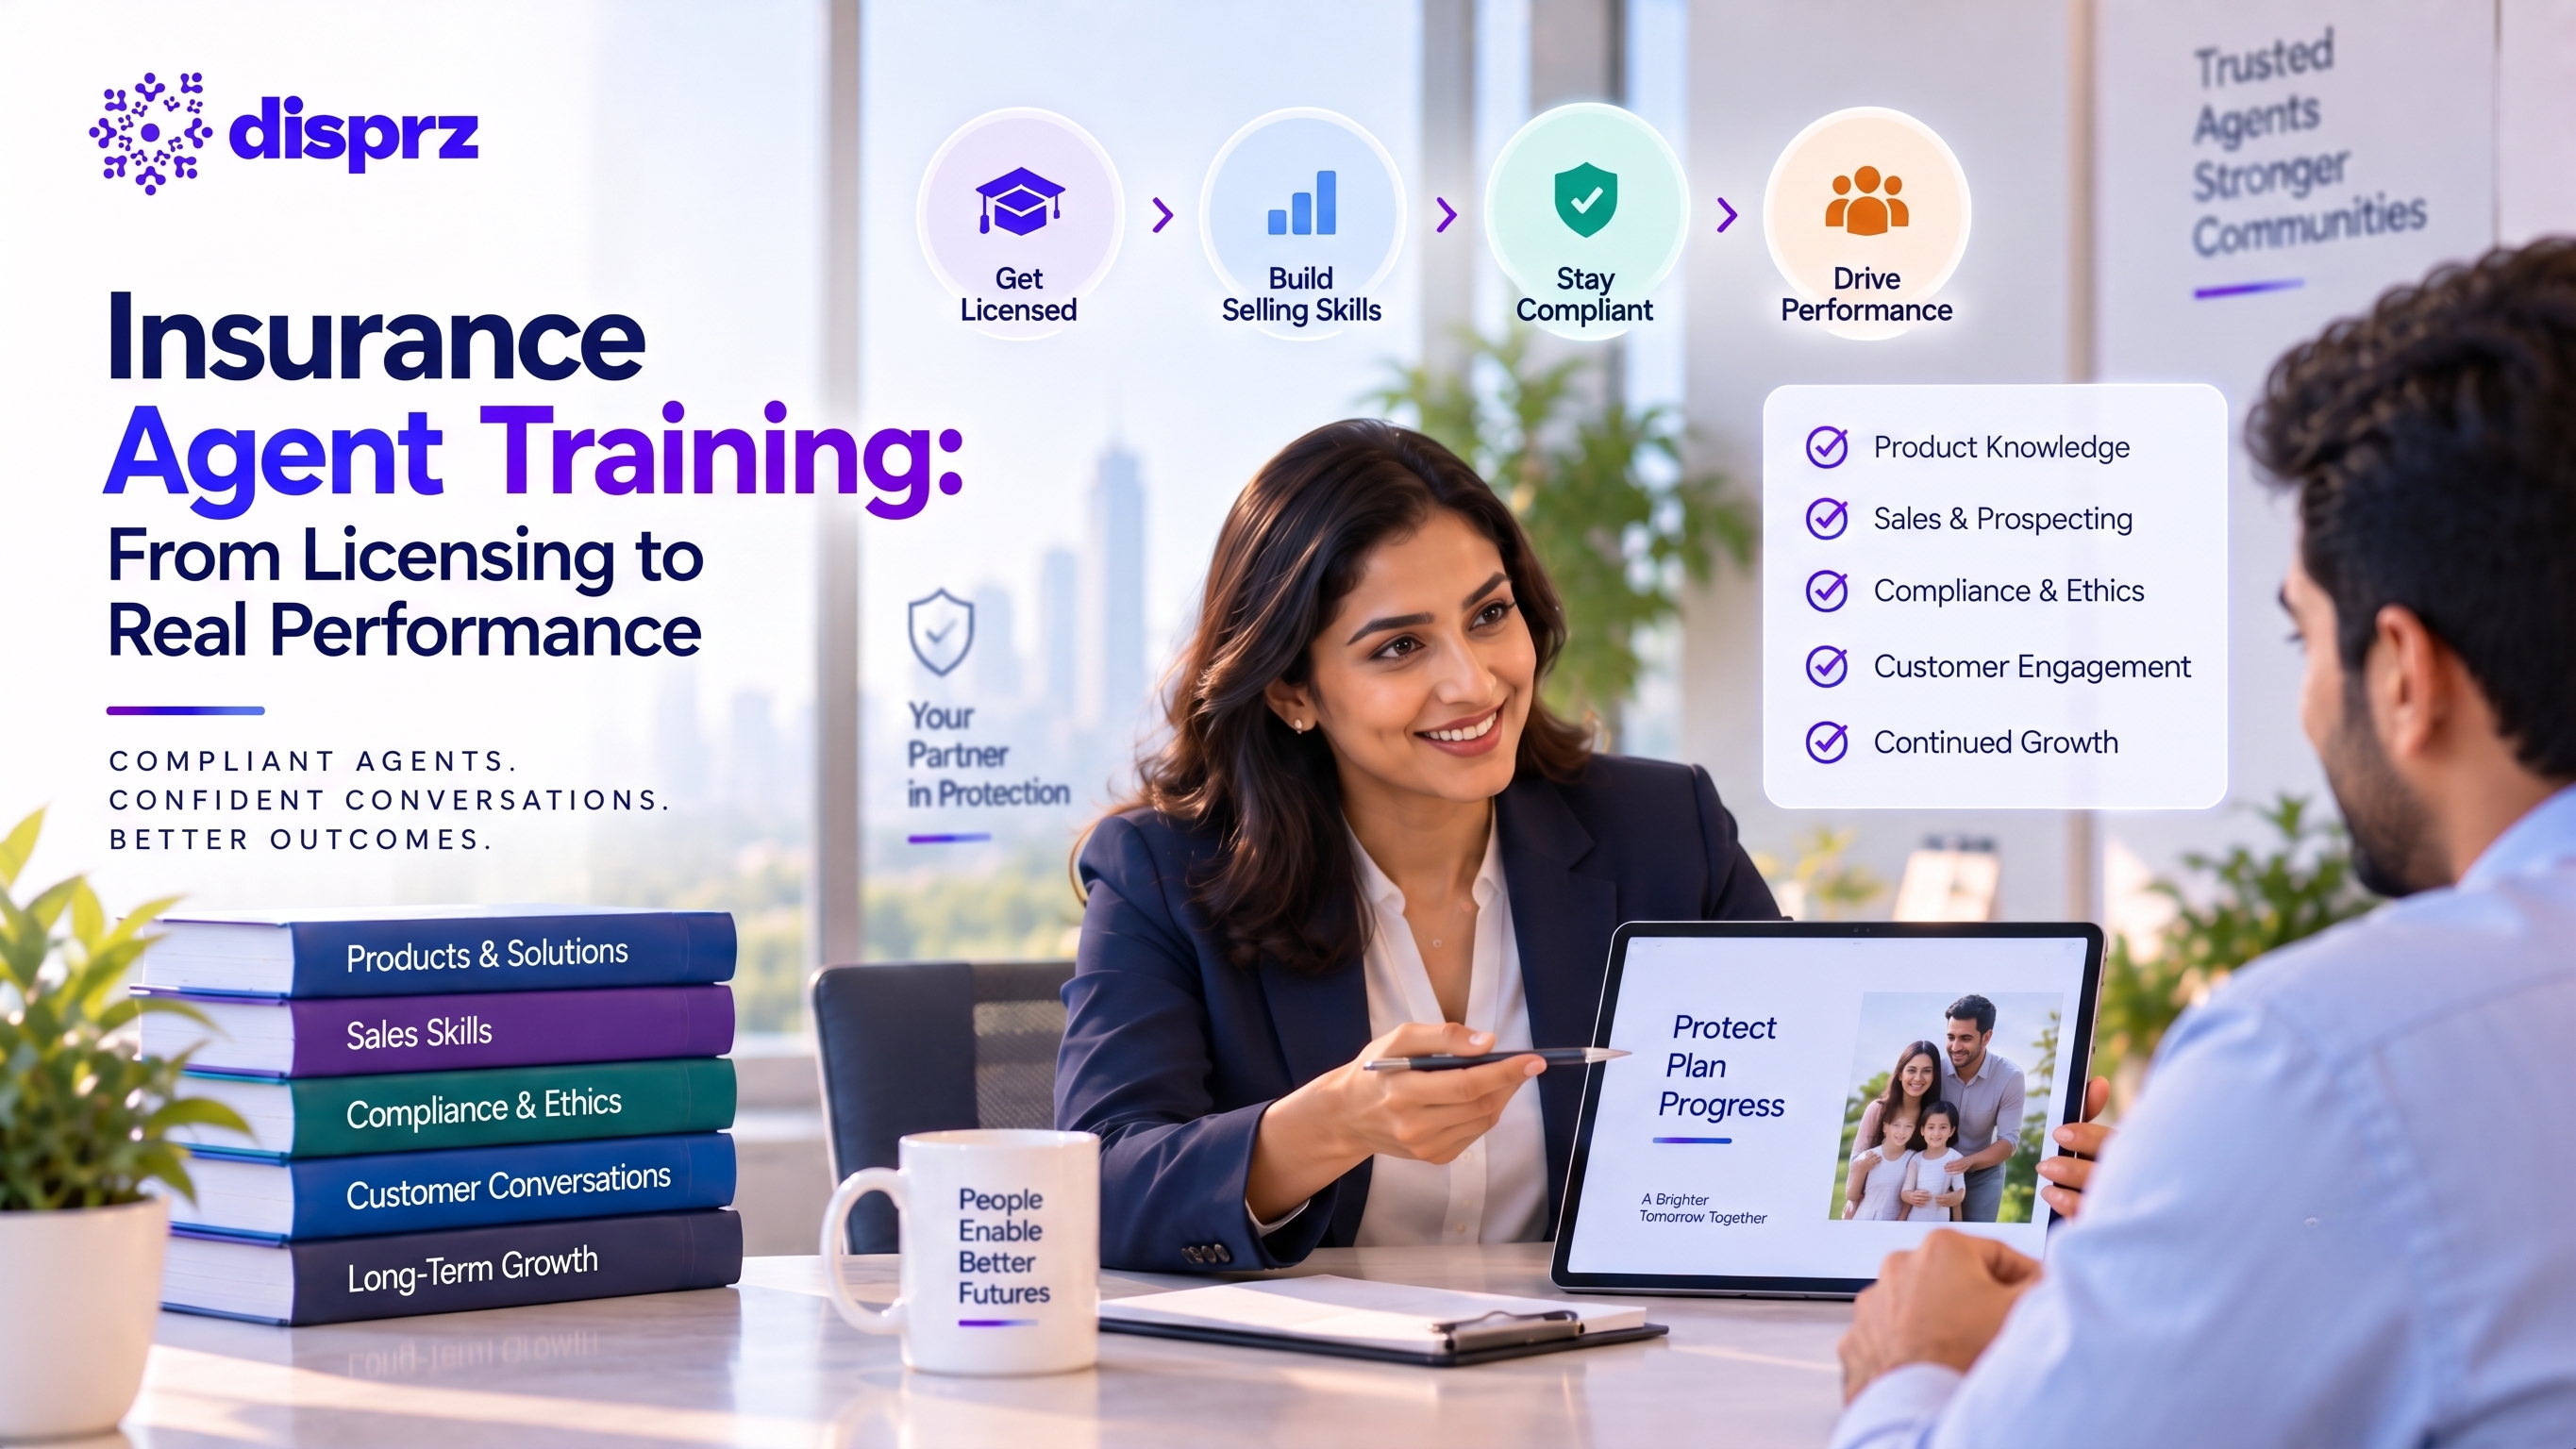
Insurance agent training splits into two things that are usually treated as one. The first is the statutory training an agent completes to become licensed. The second is everything the insurer does afterwards to make that agent productive, compliant and worth the acquisition cost. Only the first has a syllabus, a regulator and a pass mark. The second is where the money is won or lost.
TL;DR. What it is: Insurance agent training is two programmes, not one. The regulator sets a pre-licensing bar. The insurer designs everything that comes after it. Why it matters: Licensing makes an agent legal to sell. It does not make them ready. Agents leave in large numbers, and the complaints that follow are about how they sold, not whether they were trained.
Steps to take
- Diagnose last year's terminations before building any content
- Score the current programme honestly
- Decide which system owns agent identity
- Build one population's path properly before adding the rest
- Trigger refreshers from data, not the calendar
- Give managers targets, not reports
How Disprz helps: Skill mapping and role fitment scores replace completion flags. Certification tracking keeps the audit trail separate from capability. Extended enterprise access reaches agents and partners who are not employees.
What Is Insurance Agent Training?
Insurance agent training is the combination of statutory pre-licensing education that qualifies a person to be appointed as an agent, and the employer-designed programme that teaches them to sell a specific insurer's products suitably and profitably. Regulators define the first. Nobody defines the second.
In India the licensing bar is narrow and one-off. An individual completes 25 hours of training with an approved institution and passes the IC-38 examination conducted by the Insurance Institute of India. The 2016 IRDAI circular that harmonised these requirements is explicit on the point most training heads never register: for insurance agents, no renewal training is prescribed. The requirement rises to 50 hours for composite agents, and different thresholds apply to some intermediary categories, but for the individual agent the statutory obligation is a single event. No refresher. No continuing education. No proficiency retest at year three, five or ten.
Simple. Pre-licensing training proves an agent knows what insurance is. It says nothing about whether they can position your product to a farmer in a Tier-3 town, spot an unsuitable sale, or explain a surrender clause without creating a complaint.
There is one exception, and it hints at what the rest of the answer should look like. IRDAI's Master Guidelines on Anti-Money Laundering and Counter Financing of Terrorism, in force since November 2022, require insurers to run an ongoing training programme so staff are adequately trained on AML and CFT policy, and they specify that the focus of that training must differ for frontline staff, compliance staff and staff dealing with new customers. The single continuing training obligation attached to distribution is the one that explicitly refuses to be generic. Bank staff selling insurance sit under two regimes at once, because the banking regulator sets its own periodic training and record-keeping expectations on top of the insurance ones, and the insurer answers for the sale regardless of which employer trained the seller.
Other markets draw the line differently. Under the CBUAE framework, an individual seeking registration as an insurance agent must hold a recognised insurance diploma, carry at least two years of practical experience with an insurer, and attend training courses determined by the Authority, with continuing professional development set at fifteen hours for insurance broker representatives, senior management and specialised employees. An insurer operating across both frameworks runs two different compliance clocks against one commercial problem.
That commercial problem does not change by jurisdiction. Licensing produces agents who are legal to sell. It does not produce agents who sell well, stay long, or keep a book on the books.
What Should an Insurance Agent Training Program Include?
A programme worth the name covers what licensing left out, and it distinguishes between populations that most insurers train as one group. Six components do the work.
1. Separate paths for four distinct populations
Most programmes are built for a single audience when the distribution network holds at least four, each failing in a different way:
- Newly licensed agents know insurance in the abstract and nothing about your products, underwriting appetite, claims process or systems. Failure mode is time to first sale, so the test is whether they can hold one complete customer conversation end to end.
- First-year agents have made a few sales and are measured against a minimum business guarantee. Failure mode is the second and third sale rather than the first, because the first usually comes from family or immediate network. Prospecting a stranger is the missing skill, and no pre-licensing curriculum teaches it.
- Productive veterans write consistently and have not been formally trained since the day they were licensed. Failure mode is quiet obsolescence, because products, regulations and the suitability standard all changed while nothing required them to retrain. Veterans generate a disproportionate share of mis-selling complaints precisely because they are trusted and unsupervised.
- Non-agent distribution covers Point of Sales Persons, specified persons at corporate agents, and bancassurance staff at partner banks. India had 2,718,487 POSPs and 661 active corporate agents including 237 banks as at 31 March 2025, and corporate agents contributed 34.69% of individual new business premium. They sell your product, damage your brand when they sell badly, and sit entirely outside your HR system.
2. A definition of readiness that is not a completion percentage
Readiness has to be an observable behaviour tied to a business outcome. Can this agent complete a needs assessment, recommend a suitable product, and explain the exclusions without generating a complaint. If readiness cannot be stated that way, the training defaults to content coverage and the measurement defaults to completion.
3. Content mapped to the licensing gap, not the product catalogue
The agent already knows insurance principles, because IC-38 covered them. What they do not know is your appetite, your process, your edge cases and your customers. Building product training that repeats the licensing syllabus is the most common waste in agent employee onboarding programmes, and it is why so many agents describe onboarding as a repeat of the exam.
4. Compliance and capability as two separately instrumented tracks
Certification status, licence validity, AML refresh and product authorisations are binary facts needing dates, evidence and an audit trail. Capability is a gradient needing assessment. Running both through one completion report collapses two different questions into one useless number, and it is why compliance training reporting so often satisfies the auditor while telling the business nothing.
This is where a regulated distribution network needs more than standard learning features. Role-based certification, so the requirement follows the role rather than the individual. Automatic recertification when a licence or authorisation expires, rather than a manual chase. And a record that can be produced on demand during an inspection, showing who was certified, on what, on which date, against which version of the content.
5. Sequencing adapted from the 30-60-90 model rather than copied from it
Nearly every published answer on training new agents converges on the same programme: a phased 30-60-90 day plan, a mentor pairing, multi-format content and completion tracking against milestones. It is sensible advice built on three assumptions an agency channel breaks:
- The trainee is an employee whose time you control. An appointed agent is an independent intermediary paid on commission, so every hour on the plan is an hour not earning. The plan does not fail because it is badly designed. It fails because it has no authority behind it.
- A manager has capacity to mentor. Agency managers routinely carry thirty to sixty agents across a territory, so the pairing that works in a twelve-person team becomes arithmetic that does not close.
- Day 90 is the finish line. For an agent, day 90 is usually still inside the honeymoon period of selling to family and friends. The real test arrives between month four and month nine, when the personal network is exhausted. A plan ending at day 90 stops one step before the thing that actually causes termination.
Keep the sequencing discipline. Discard the assumption that ninety days is the horizon or that a commission-paid intermediary can be scheduled like staff.
6. Measurement built on persistency rather than completion
Five numbers carry the programme, and the one most often reported is not among them:
- Time to first sale by cohort tells you whether onboarding works.
- Time to minimum business guarantee tells you whether the first-year programme works.
- Twelve-month agent survival by cohort tells you whether either is durable.
- Thirteenth-month and sixty-first-month persistency on policies each cohort writes tells you whether the agent sold suitably or sold anything.
- Complaint rate per thousand policies by tenure band tells you where mis-selling originates, and it is usually not where the training team assumes.
Completion rate belongs in none of these. It is an input measure promoted to an outcome measure because it is the easiest thing to produce.
which industry need Insurance Agent Training and his pain?
The obvious answer is insurance. But the requirement lands differently across segments, and the pain is sharpest wherever distribution is largest and least controlled.
| Segment | Scale of the distribution force | Where it breaks | What the programme has to fix |
|---|---|---|---|
| Life insurers | 3.12 million agents. 1,115,026 appointed and 887,020 terminated during 2024-25 | Eight agents leave for roughly every ten who join, most of them on minimum business guarantees | Time to first sale, then prospecting beyond the personal network |
| General and standalone health insurers | Industry-wide, 1,487,473 appointed and 941,935 terminated in the same year, with health insurers growing fastest | Onboarding volume outruns onboarding capacity | Product and claims depth at speed, without repeating the licensing syllabus |
| Banks and corporate agents | 661 corporate agents including 237 banks, contributing 34.69% of individual new business premium | The insurer carries the reputational and regulatory risk while the bank owns the employment relationship and the HR system | Suitability standards and access for people the insurer cannot assign training to |
| Point of Sales Persons | 2,718,487 as at 31 March 2025 | A narrow product set sold with minimal supervision and no employment relationship | Repeatable product training and a certification trail that survives an audit |
Source for all figures: IRDAI Annual Report 2024-25, Tables II.1, II.3 and II.10.
Life insurers carry the heaviest exposure. Their net agency force grew from 2.90 million to 3.12 million last year, a 7.87% rise that looks healthy until the gross flows underneath it are visible. Almost nine hundred thousand terminations sit inside that growth. Most trace to failure against minimum business guarantees, which is another way of saying the agent never reached productivity.
At replacement rates near 80%, the usual training economics invert. A long, expensive onboarding programme is mostly spent on people who will not be there in twelve months, so the return comes from shortening the path to the first few sales rather than from depth of coverage. Depth belongs later, with the cohort that survives.
Market. Individual agents still account for 49.44% of individual new business premium in Indian life insurance, down from 50.90% the previous year. The channel is simultaneously the largest single source of new business and the one shedding people fastest.
Three more figures from the same report turn this from an HR problem into a board problem:
- Commission outgo rose 18% while total premium grew 6.73%
- The commission expense ratio climbed from 6.21% to 6.86%
- New individual policies fell 7.39%, with 27.0 million written against 29.2 million the year before
Distribution cost is rising close to three times faster than premium while policy count falls. An insurer in that position pays progressively more to acquire and re-acquire people who write progressively less.
The pain that shows up in complaints rather than churn
Grievances against Indian life insurers in 2024-25 were essentially flat, 120,429 against 120,726 the previous year. But grievances categorised as Unfair Business Practices rose from 23,335 to 26,667, an increase of roughly 14%, lifting that category from 19.3% to 22.1% of all life complaints (IRDAI Annual Report 2024-25, Table II.16). Total noise held steady. The mis-selling share of it grew.
IRDAI's own prescription reads like a training brief written in regulatory language. Insurers are advised to conduct root cause analysis, assess product suitability, and implement distribution channel-specific controls. Not more training. Channel-specific controls.
Every one of those agents passed IC-38. Completion was 100%. The outcome was a 14% rise in complaints about how they sold.
If completion dashboards look healthy while incidents and complaints climb, the dashboard is measuring the wrong variable. Completion confirms exposure to content. Nothing in it reports whether the agent applied a suitability test to the customer in front of them.
Mistakes. Reporting completion percentages to the board as evidence of a trained distribution force. Completion measures whether content was consumed. It cannot distinguish an agent who understands suitability from one who clicked through the module on a shared phone during a branch visit.
The operating conditions the content has to survive
Four constraints shape what can actually be delivered to an agency force:
- Agents are frequently not employees: They hold an appointment letter, not a contract of service, so there is no HRIS record, no corporate email, no single sign-on and no company-controlled device. Any system assuming an employee identity excludes the largest part of the network by default. Training people who have no company email address is the same structural problem as extending learning to channel partners or franchisees, and it takes the same answer: an identity the organisation issues and controls without an employment record behind it.
- Coverage is geographic rather than central: Indian life insurers operated 12,210 offices as at 31 March 2025, with around 40% outside Tier I cities and offices reaching 93% of districts. The agent in a district town has intermittent connectivity, a mid-range Android phone shared at home, and no quiet hour for a 45-minute module.
- Language is not uniform: An agent in a Tier-3 market often runs the entire customer conversation in a regional language while the collateral, the compliance module and the assessment exist only in English. That translation happens alone and unsupervised, and it is a direct source of unsuitable sales.
- Attention is transactional. Commission-paid agents treat learning time as lost earning time, so training competes with income rather than with other work.
Design against those four and the requirements become specific: short modules, vernacular delivery, offline capability, mobile-first, and assessment completable in a market rather than at a desk. Programmes built this way reach completion rates above 45% against an industry average below 30%, the same pattern seen in frontline training and enablement across retail and field operations.
Steps to start Insurance Agent Training on your workplace
Six steps, in order. The sequence matters more than the speed, because three of these are cheap to do first and expensive to retrofit.
Step 1. Diagnose the terminations before designing the curriculum
Pull last year's termination list and segment it by tenure at exit. Then find out how many of those agents completed onboarding.
If most of them did, the content was never the constraint. Agents leaving because the minimum business guarantee is unrealistic for the territory, because lead flow is absent, or because commission structures punish the first year will not be retained by training, and training will be blamed when it does not retain them.
Step 2. Score where the programme actually stands
Work through the table below and total the score. It takes twenty minutes and it prevents the most common failure, which is building content for a problem the organisation does not have.
| Question | 0 points | 1 point | 2 points |
|---|---|---|---|
| Can you state readiness as an observable behaviour? | No definition exists | Defined but not assessed | Defined, assessed, scored |
| Does post-licensing content repeat the licensing syllabus? | Largely yes | Partly | Deliberately not |
| Are compliance status and capability reported separately? | One report | Two reports, one system | Separate, both audited |
| Can partner and non-employee sellers access training? | No | Manual workaround | Native extended access |
| Is content available in the language of the sale? | English only | Some translation | Vernacular by default |
| What triggers a veteran refresh? | Annual calendar | Calendar plus ad hoc | Data signals |
| Do managers get targeted flags or full reports? | Full reports | Filtered reports | Individual risk flags |
| Is any training metric tied to persistency? | No | Correlated informally | Tracked together |
Twelve to sixteen and the programme is designed. Six to eleven and it is functioning but blind in places. Below six and the organisation is running licensing compliance rather than an agent training programme.
Step 3. Settle which system owns agent identity
Agent data typically lives in an agency management system rather than an HRIS, and the two rarely share a person identifier. Certification status may sit in a third system owned by compliance.
Standing up a learning management system before resolving this produces duplicate records, agents who cannot log in, and a certification report nobody trusts. Solve it before procurement, not after.
Step 4. Build for one population first
Pick whichever of the four populations is currently costing the most and build that path properly, rather than launching a thin programme for everybody.
First-year agents are usually the right starting point. That is where terminations concentrate, and where improvement shows up fastest in cohort data.
Step 5. Set the veteran trigger to data rather than the calendar
Annual refresh cycles are cheap to administer and weak at changing behaviour. Better triggers already sit in data the insurer holds: a product change, a regulatory amendment, a complaint spike at a specific branch, or a persistency fall in a specific cohort.
Step 6. Give managers targets, not reports
The realistic ask is not more coaching hours but better targeting. Tell the manager which three agents in a team of forty are drifting and on what, rather than sending a completion report for all forty.
Where practice volume rather than manager attention is the constraint, simulation is the honest answer, and the mechanics sit in how you reduce ramp time for field sales roles generally.
Before you commit: when not to do this at all
An insurer with a few hundred agents in one geography, selling two products, with managers who genuinely know every agent, will get more from structured manager coaching than from a platform. Scale is what makes systematisation pay, and the threshold is real.
There is also a limit on automation. Generating product microlearning from an approved product guide is low risk. Generating suitability guidance or regulatory interpretation without a named human reviewer is not, because in a mis-selling investigation the question will be who approved the material the agent relied on.
How Can Disprz Help Streamline Insurance Agent Training?
Everything above is a system-of-record problem as much as a content problem: four populations with different journeys, a non-employee majority, a certification clock, a language requirement, and an outcome measure living in the policy administration system rather than the learning one.
Disprz is built for that shape. Skill mapping defines what an agent at each stage needs to be able to do and at what proficiency, and assessment produces a role fitment score rather than a completion flag, so readiness becomes a number the agency head can act on. Certification and licence tracking handles renewals, reminders, completion records and audit logs for the compliance track without contaminating the capability track. Turo turns your own product guides and regulatory circulars into role-specific microlearning 80% to 90% faster than a conventional authoring cycle, with human review in the loop. That matters most before a product launch, when distribution has to be trained on the new proposition and its suitability boundaries in the window between sign-off and go-live. Extended enterprise access covers POSPs, corporate agent staff and bancassurance partners who never appear in the HR system. Mobile-first delivery is the default rather than a port.
The part that decides whether any of it was worth doing is the analytics layer, which connects learning activity to sales KPIs and persistency ratios rather than stopping at completion. ROSHN, a Disprz customer in real estate rather than insurance, attributed 15% annual business growth to its Disprz-powered programme, and the mechanism behind that attribution is the same one an insurer would point at persistency. Across 3.5 million learners in 500+ organisations and 25+ countries, the pattern holds that programmes tracking a business metric survive budget cycles and programmes tracking completion do not.
One caution worth stating plainly, because the vendor category rarely does. McKinsey's insurance research puts domain-level AI rewiring at a 10% to 20% improvement in new-agent success rates and sales conversion, and is equally blunt that change management represents roughly half the effort required to secure it, advising at least a dollar on adoption for every dollar on development. Budget for the rollout, not only the platform. Adoption after go-live is a distribution management problem more than a learning one, and it is won by agency managers pushing it inside their weekly rhythm rather than by launch communications.
The insurance solution covers how these pieces fit together across agent and employee populations at once.
The licence tells you an agent is permitted to sell. Everything determining whether they are still selling in eighteen months is yours to design, and nobody is going to specify it for you.
Frequently asked questions
What insurers ask most often about agent training.
What is insurance agent training?
Insurance agent training covers two distinct programmes. Statutory pre-licensing training qualifies a person to be appointed as an agent, and in India that means 25 hours plus the IC-38 examination. Employer training covers products, suitability, systems, prospecting and ongoing compliance, and carries no prescribed syllabus.
How long is insurance agent training in India?
Insurance agent training in India requires 25 hours of training from an approved institution for individual agents, and 50 hours for composite agents covering life and general business. IRDAI prescribes no renewal training for individual agents, so any continuing programme after licensing is designed by the insurer rather than the regulator.
How do you train new insurance agents effectively?
Training new insurance agents effectively starts with defining readiness as an observable behaviour rather than a completion percentage. Cover what licensing did not: your products, your underwriting appetite, your claims process and prospecting beyond personal networks. Sequence it in short mobile modules in the language the agent sells in.
Is AML training mandatory for insurance agents?
AML training carries an ongoing obligation in India under IRDAI's Master Guidelines on AML and CFT. Insurers must run a continuing training programme on AML and CFT policy, and the guidelines require the focus to differ between frontline staff, compliance staff and staff dealing with new customers rather than applying one generic module.
Why do so many insurance agents leave in the first year?
Insurance agents leave in the first year largely because they miss minimum business guarantees. Early sales tend to come from personal networks, and the second and third sale requires prospecting strangers, a skill no pre-licensing curriculum teaches. Termination follows failure to produce rather than failure to learn the syllabus.
What should insurers measure instead of training completion?
Insurers should measure time to first sale by cohort, time to minimum business guarantee, twelve-month agent survival, thirteenth-month persistency on policies each cohort writes, and complaint rate per thousand policies by tenure band. Completion measures content consumption and cannot distinguish a ready agent from a compliant one.
How do you train agents who are not employees?
Training non-employee distribution requires extended enterprise access that does not depend on an HRIS record, corporate email or company-managed device. Point of Sales Persons, corporate agent staff and bancassurance partners need their own identity, assignment logic and certification tracking, separate from employee populations but held to the same evidence standard.
About the authors
Abhijit Rao
AVP & Business Head - India | Expert Reviewer
Abhijit Rao is a senior business and sales leader with extensive experience helping organizations address workforce capability, learning, and skilling needs across large and distributed teams. His ...
Reviewed for accuracy on 15 Sep 2026